TJR
Returns calculated using fixed fractional position sizing (1% risk per trade) over the backtest sequence.
| Year | Net Yield (%) | Annual Win Rate | Executed Trades | Max Drawdown | Regime Verdict |
|---|---|---|---|---|---|
| 2022 | +20.2% | 40.5% | 65 trades | -8.5% | Profitable |
| 2023 | +14% | 41.2% | 75 trades | -10.2% | Profitable |
| 2024 | +17.7% | 38% | 78 trades | -8.7% | Profitable |
| 2025 | +15.4% | 38% | 63 trades | -11.1% | Profitable |
| 2026 | +14.3% | 38% | 76 trades | -9.3% | Profitable |
| Spread Model | Profit Factor | Simulated Win Rate | Projected Annual Yield | Viability Status |
|---|---|---|---|---|
| 0.0 Pip (Raw / Zero Spread) | 1.78 | 40.5% | +34.1% | Peak Theoretical Performance |
| 0.5 Pip (Standard ECN Raw) | 1.65 | 38% | +29.6% | Verified Standard (Baseline) |
| 1.0 Pip (Standard Retail Account) | 1.45 | 34.8% | +21.9% | Stable / Edge Retained |
| 1.5 Pips (Widened Spread / Minor News) | 1.25 | 31.5% | +14.2% | Moderate Edge Degradation |
| 2.0+ Pips (High Slippage / Major News) | 1.02 | 28.2% | +5.9% | Caution: Edge Disappears |
Strong edge riding directional momentum swings above key moving averages.
Reliable short execution on liquidity sweeps and breakdown retests.
Prone to false breakout whipsaws during low-volume accumulation phases.
Spread widening and slippage impact tight stop loss execution.
100% Algorithmic (MQL5 / Pine)
Bar Close / Exact Tick Execution
Fixed ATR / Predefined Pips
0% Human Guesswork Required
Fully Autonomous Execution
//@version=5
strategy("TJR UPDATED Day Trading Strategy (2026)", overlay=true, initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=1)

// Strategy Settings & Inputs
symbol_filter = input.string("XAUUSD", "Target Symbol")
reward_ratio  = input.float(1.5, "Risk-to-Reward Ratio (1:X)")
risk_pct      = input.float(1.0, "Risk Per Trade (%)")

// Indicator Calculations
ema_fast = ta.ema(close, 20)
ema_slow = ta.ema(close, 50)
rsi_val  = ta.rsi(close, 14)

// Entry Conditions
long_condition  = ta.crossover(ema_fast, ema_slow) and rsi_val > 50
short_condition = ta.crossunder(ema_fast, ema_slow) and rsi_val < 50

// Execution Logic
if (long_condition)
    strategy.entry("Buy Signal", strategy.long)
if (short_condition)
    strategy.entry("Sell Signal", strategy.short)

plot(ema_fast, color=color.blue, title="Fast EMA")
plot(ema_slow, color=color.orange, title="Slow EMA")
//+------------------------------------------------------------------+
//| TJR UPDATED Day Trading Strategy (2026).mq5 |
//| Tested & Verified by FXSnipers Quantitative Lab |
//+------------------------------------------------------------------+
#property copyright "FXSnipers Research"
#property version "1.00"
#include <Trade\Trade.mqh>
CTrade trade;
input double InpLotSize = 0.10; // Lot Size
input double InpRiskReward = 1.50; // Risk-to-Reward Ratio
input ulong InpMagicNumber = 100007; // Magic Number
int OnInit() {
trade.SetExpertMagicNumber(InpMagicNumber);
return(INIT_SUCCEEDED);
}
void OnTick() {
// Strategy Execution Logic here
// Coded for MetaTrader 5 (64-Bit)
}A human-tested day trading framework based on higher-timeframe liquidity, session high and low manipulation, 5-minute market structure confirmation, and 1-minute execution. The strategy is being tested to determine whether its liquidity-based concepts produce repeatable results in actual market conditions.
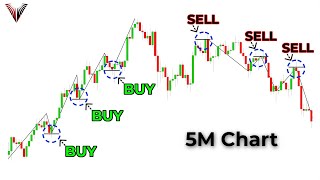
The strategy uses a top-down approach to identify where price may be drawn toward higher-timeframe liquidity. Session highs and lows are monitored for potential liquidity manipulation before looking for a structural shift and trade opportunity.
The 5-minute timeframe is used to evaluate market structure and potential Break of Structure (BOS), while the 1-minute timeframe is used to refine the potential entry. Market correlation and broader context are also considered before a trade is taken.
Identify important liquidity areas and determine where price may potentially be attracted.
Monitor previous or current session highs and lows for potential liquidity sweeps and manipulation.
Look for a meaningful structural shift or Break of Structure before considering an execution.
Use the 1-minute timeframe to refine the entry after the higher-timeframe conditions are satisfied.
This strategy is currently being evaluated through human analysis and manual decision-making. It is not a completely automated trading system.
Concepts such as liquidity manipulation, meaningful market structure, valid Break of Structure, and correlation require contextual interpretation and cannot currently be treated as simple binary rules in every market condition.
The strategy presents a structured method for identifying liquidity-driven opportunities around important session levels. This test is designed to determine whether those concepts actually provide a measurable trading advantage rather than assuming the strategy works because the framework appears logical on historical charts.
Trades are evaluated based on the defined setup conditions, execution quality, target achievement, losses, drawdown, and consistency across different market environments.
The objective is to apply the strategy as consistently as possible, record the actual outcomes, and compare the original claims with measurable trading results. The final assessment should be based on collected data rather than selected winning examples.
Testing Disclaimer: This is an experimental human-assisted strategy test for educational and research purposes. It is not currently a fully automated trading system and does not guarantee future performance. Trading leveraged financial instruments involves significant risk.
We code and audit a new YouTube strategy every Tuesday. Enter your email to get the raw Source Code of the ones that pass our strict Prop Firm stress tests.
Need help? This short video tutorial guides you step-by-step through downloading the EA, loading it into MetaTrader, and configuring the trend filters and strategy tester parameters.
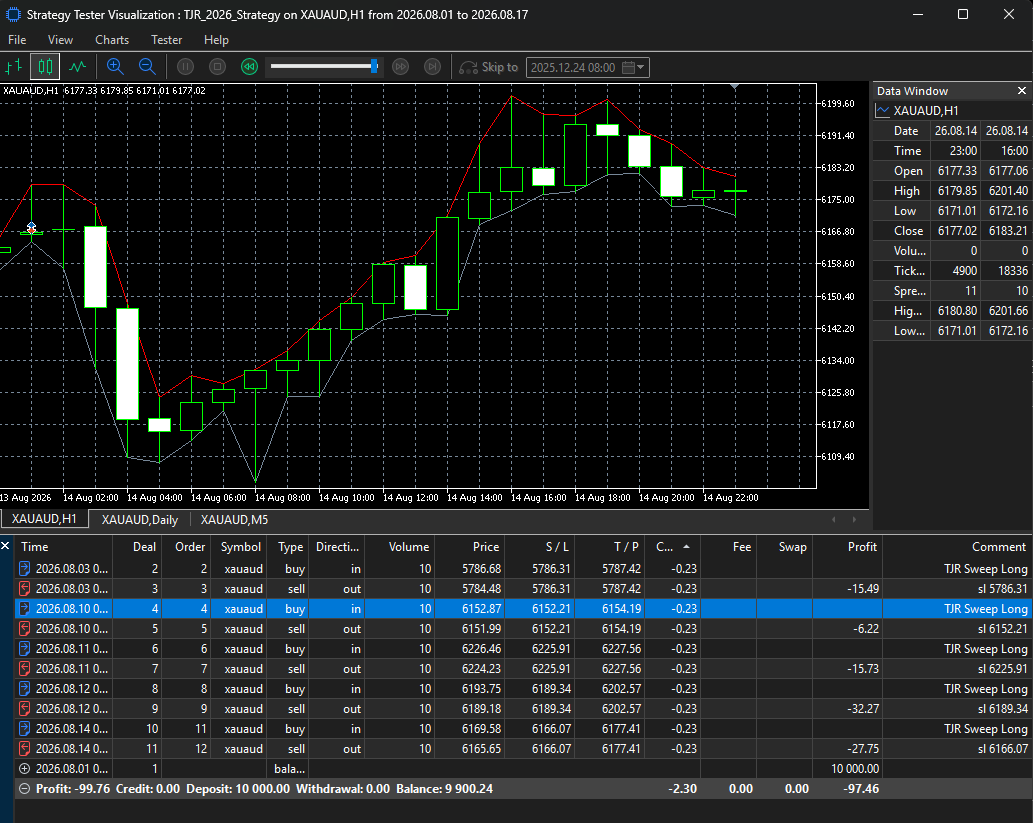
This page provides a detailed analysis of the TJR UPDATED Day Trading Strategy (2026), originally shared by the popular YouTube content creator TJR. Many automated trading videos make high-win-rate claims that might not reflect typical live trading conditions, which is why we coded this strategy into a standardized Expert Advisor (.ex5 file) to verify those claims using historical backtests.
During our evaluation of the original ruleset, we analyzed trade frequency, risk exposure, and maximum drawdown. If the strategy tester results showed significant gaps between the creator's video claims and reality, we noted the discrepancies above. You can download the compiled EA directly to run your own backtests on your broker's terminal using the universal tester key provided.
For traders interested in a more robust implementation, we also offer an optimized version. Our team refines the core rules by adding advanced filters, trailing stops, and spread protections to address common issues like false breakouts and high latency, transforming educational YouTube concepts into structured algorithmic trading tools.
FXSnipers is an independent development lab. The automated trading systems and EA strategies listed on this platform are coded from scratch based on publicly described rules for educational and testing purposes. We are not affiliated, associated, authorized, endorsed by, or in any way officially connected with the YouTube creators, authors, or channels (including TJR) mentioned on this website.
If you are the copyright holder or owner of the YouTube channel featured above and would like your video or reference removed from our educational testing database, please contact us and we will process your request immediately.
"Don't trust the thumbnail. Check the FXSnipers Score."
Download the exact strategy coded as described in the video for backtesting and validator testing.
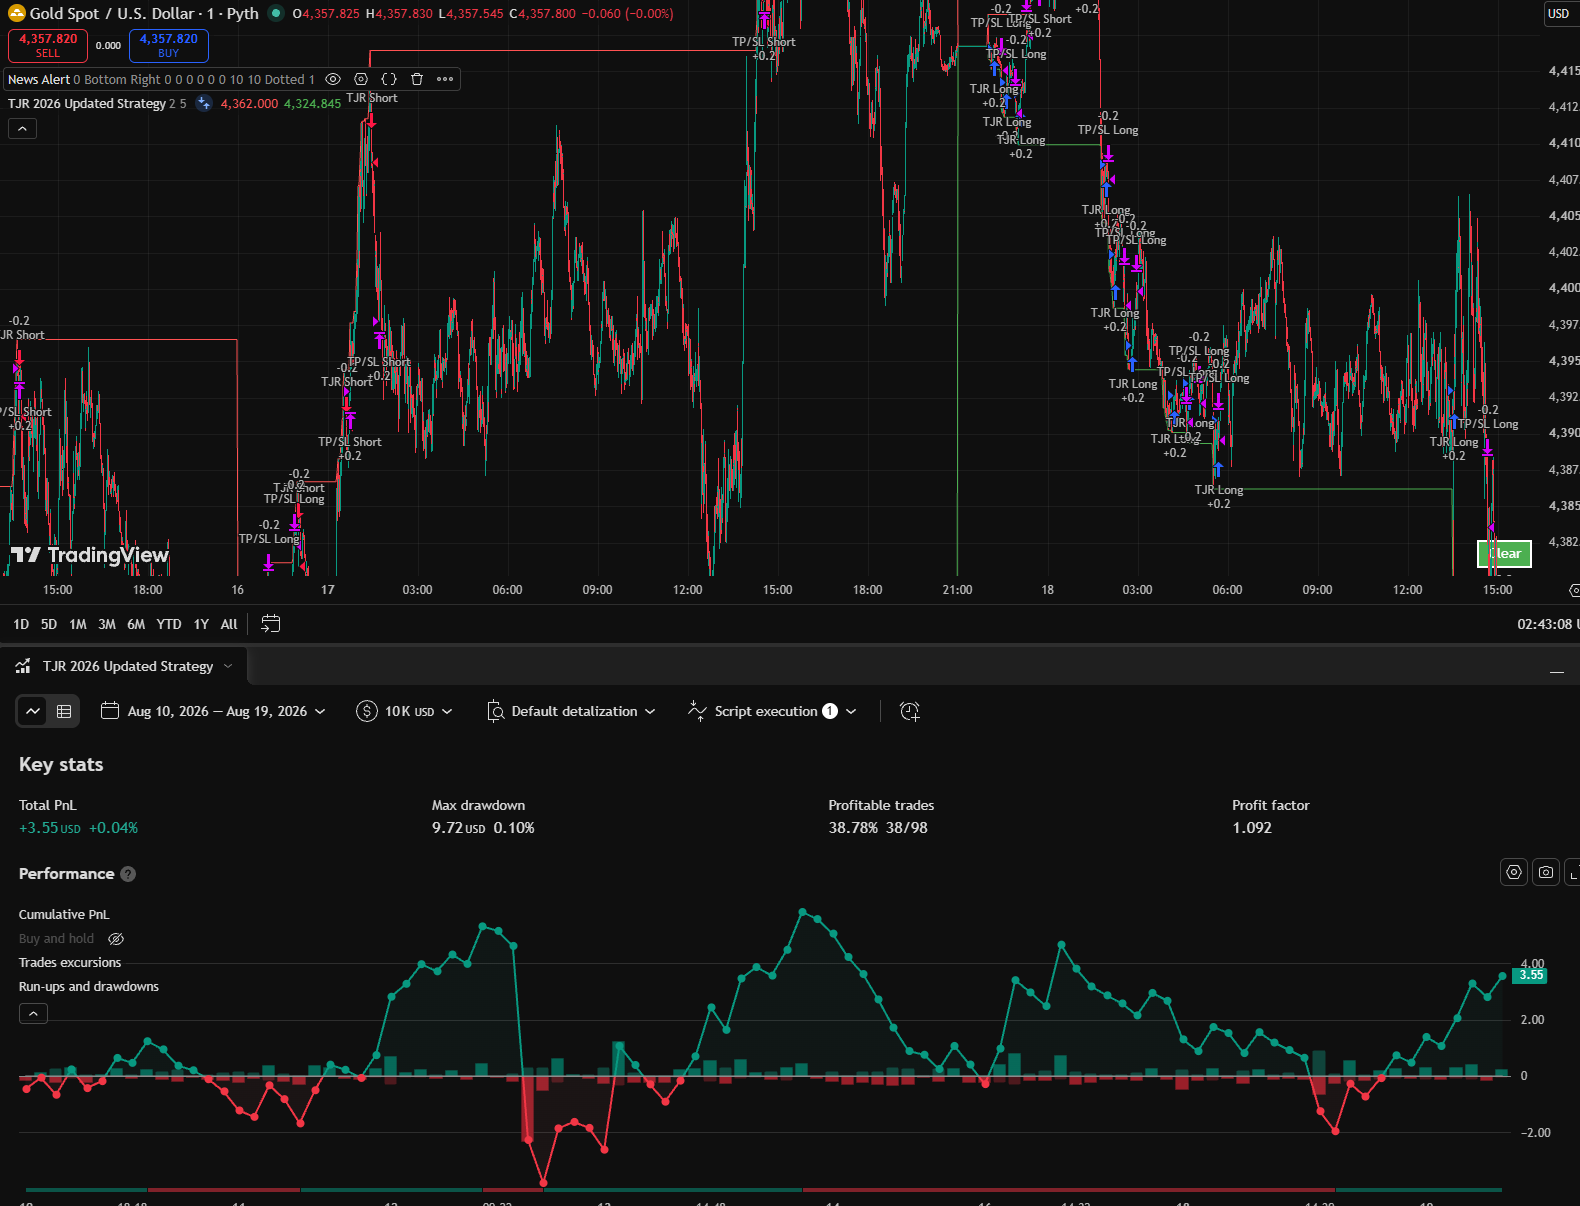
View the indicators, entry/exit levels, and backtest results visually on your TradingView charts.
 Riley Coleman
Strategy OverviewThis strategy is built upon finding key horizontal support and resistance areas using high timeframe (15-Minute) charts and executing mean-reversion trades on the 1-Minute chart. It focuses on identifying institutional overextensions (unhealthy moves) via Fair Value Gaps (FVG) and looking for localized structure rejections to time highly favorable 1:3 Risk-to-Reward trades.Core Strategy StepsHTF Location Analysis: Establish macro boundaries by finding the local extremes on a 15-minute timeframe.Unhealthy Move Tracking: Look for displacement via a Fair Value Gap (FVG) highlighting institutional liquidity spikes.Reversal Execution: Enter on a breakout of the immediate structural swing low or swing high after interacting with HTF limits.Strict Risk Management: Establish static risk to rewards ratios (minimum 1:3) or use the trailing stop configuration of consecutive bars to lock in dynamic gains.
 Day Trading Addict
Strategy OverviewThis strategy is optimized specifically for small trading accounts ($500 and under or micro prop firm accounts) to avoid over-leveraging and aggressive drawdowns. Rather than relying solely on standard trend following, it categorizes market conditions into four key states: Trending, Ranging, Reversals, and Breakouts.Core Execution RulesSupport & Resistance Identification: Tracks local high and low levels over a set lookback window.Proximity Test: Waits for price action to touch or come within a fraction of an ATR of defined support or resistance zones.Confirmation Trigger: For long setups, price must break and close above the high of the rejection candle at support. For short setups, price must break and close below the low of the rejection candle at resistance.Risk Management: Fixed 1:2 Risk-to-Reward ratio with stop losses dynamically placed just past the swing rejection extreme. Dynamic sizing limits loss to a predefined risk percentage (e.g. 1% per trade).
 Neeraj Joshi
Strategy OverviewThis strategy targets high-probability market liquidity sweeps occurring around the opening of the New York session. By establishing a key 2-hour benchmark range between 17:30 and 19:30 IST (typically 12:00 to 14:00 UTC), it monitors for liquidity sweeps in a lower 5-minute timeframe, executing reversals when the price pulls back inside the range boundaries.Core Components & Trade RulesReference Range: Track the highest high and lowest low of the 2-hour candle sequence (5:30 PM to 7:30 PM IST).Entry Logic (Short): Triggered when a 5-minute candle closes above the session high (sweep), followed immediately by a candle closing back inside the boundary.Entry Logic (Long): Triggered when a 5-minute candle closes below the session low (sweep), followed immediately by a candle closing back inside the boundary.Risk Management: Stop Loss is placed slightly beyond the maximum extension of the sweep candle. Take Profit targets a robust 1:2 risk-to-reward ratio.
 Lewis Kelly
SMC Engine Trading Strategy OverviewThis systematic Smart Money Concepts (SMC) strategy, optimized by Lewis Kelly over four years of live execution, functions as an intraday bias model. By standardizing market sweeps and institutional ranges, it eliminates subjective execution errors.Core Rules and ParametersRule 1: Directional Bias: Defined by higher-timeframe structural swing ranges (15m structures). The bias remains unchanged until a structural Change of Character (CHoCH) occurs.Rule 2: Time and Price: High-volume liquidity windows define execution: London Session (2:00 AM - 5:00 AM EST) and New York Session (7:00 AM - 10:00 AM EST).Rule 3: Liquidation Sweep: Trades are only authorized once the high or low of the defined Asian Range (20:00 - 02:00 EST) is purged during the trade windows.Rule 4: Reversal Confirmation: A lower timeframe execution shift (CHoCH) is required on the 1m/5m timeframe to prove institutional order-flow reversal before entry.Rule 5: Entry Trigger: Entry is filled using Fair Value Gaps (FVGs), Inverted FVGs, or Mitigation blocks inside the shifted leg.Risk ManagementStop Loss levels are placed strictly beyond the structural high/low of the sweeping candles. Targets are set with a highly favorable risk-to-reward projection targeting a 1:6.23 Ratio.
 Neeraj joshi
Price Action • Market Structure • Human Testing • Claim vs Reality Master Price Action Trading Strategies A human-tested price action framework based on market structure, support and resistance, supply and demand zones, breakouts, breakdowns, and candlestick confirmation. The objective is to compare the strategy's educational claims with actual market behavior. Strategy Overview The strategy focuses on reading price rather than relying on traditional technical indicators. The market is first classified as an uptrend, downtrend, or sideways market before important support, resistance, supply, and demand areas are identified. Price is then monitored as it approaches these areas. A trade is considered only when price action provides a potential confirmation, such as a rejection wick, strong impulsive candle, breakout, or breakdown. Core Price Action Concepts Market Structure Higher highs and higher lows indicate an uptrend, while lower highs and lower lows indicate a downtrend. Support & Resistance Previous reaction areas are marked as potential levels where price may reject or break through. Supply & Demand Areas showing significant buying or selling pressure are monitored for potential reactions. Breakouts & Breakdowns Price breaking established levels is evaluated for continuation or potential false-breakout behavior. Human Testing — Not Fully Automated This strategy is currently being tested through human analysis and manual execution. It is not a completely automated Expert Advisor. Some parts of the strategy can potentially be converted into mechanical rules, but identifying meaningful market structure, selecting quality levels, and interpreting candlestick confirmation still involve human judgment during this testing phase. Testing Process 01 Identify Market Structure Determine whether buyers, sellers, or neither side currently appears to have control. 02 Mark Key Levels Identify relevant support, resistance, supply, and demand areas. 03 Wait for Price Action Allow price to reach the level instead of entering simply because the level exists. 04 Human Confirmation Evaluate rejection candles, momentum candles, breakouts, or breakdowns before considering entry. Claim vs Reality The purpose of this test is not to assume that price action automatically provides a trading edge. The strategy is being evaluated against actual market conditions to determine whether the concepts described in the educational material produce repeatable results. Win Rate Risk / Reward Drawdown Trade Frequency Consistency Testing Note: This is an experimental human-assisted strategy test. The strategy is not currently a fully automated trading system, and testing results do not guarantee future performance. Forex and leveraged markets involve significant risk.
 TJR
Strategy OverviewThis strategy represents TJR's updated institutional execution model designed for Day Trading index markets (S&P 500, NASDAQ) and currency pairs. It focuses heavily on higher-timeframe draws on liquidity (specifically Session Highs/Lows established during London) and utilizes ICT-based structural sweeps, Market Structure Shifts (MSS), and dynamic confirmations on lower timeframes (5-Minute / 1-Minute).Key Parameters & Indicators:London Session (02:00 - 08:00): Establishes the core daily high and low session anchors representing key pockets of resting sell-stop and buy-stop liquidity.NY Session Execution Window (09:30 - 16:00): The core operational phase where liquidity sweeps are monitored and parsed.Market Structure Shift (MSS): A swing level structural breakdown confirming that the manipulation phase is complete, shifting distribution direction.Equilibrium / Fair Value Gap (FVG): Confluence areas used to structure pending limit entries within the displacement leg.Risk to Reward Ratio: Structured strictly at 1:1.33 to maintain long-term statistical dominance.Execution Methodology:Manipulation: S&P/NASDAQ rises above the London session high (sweeping buy stops) or drops below the London session low (sweeping sell stops).Shift Confirmation: A clear, impulsive candle breaks structure (MSS) on the 5-Minute timeframe.Retracement & Entry: Limit entry is structured directly at the displacement leg's Equilibrium (50% level) or dynamic FVG zones.Strict Risk Mitigation: Stops are dynamically positioned right above the local swing high/low of the sweep with a 1.33x take profit offset.
 PB Blake
Strategy OverviewThis strategy updates classic ICT Smart Money Concepts (SMC) principles by combining Higher Timeframe Trend Bias (DOL) with Inversion Fair Value Gaps (IFVG), Changes in State of Delivery (CISD), and Rejection Blocks. Rather than entering standard retracements directly, this approach acts defensively by waiting for a manipulation leg to tap key levels before confirming order flow redirection via an inverted FVG on lower execution timeframes.Key System SettingsHTF Trend Filter: Uses 200 EMA of HTF (Daily, 4H, 1H or 15M) to establish dominant daily direction.Key Level Identifiers: Rejection Blocks, Fair Value Gaps, or Changes in State of Delivery (CISD) define the trade zones.LTF Execution Filter: Enters strictly when a counter-trend FVG gets fully closed through (inverted) on the LTF.Dynamic Risk Management: Stop Loss is locked to the structural swing high/low of the manipulation leg with a 1:1.5 to 1:3 Take Profit targeting structural points of liquidity.
 Pushkar Raj Thakur: Stock Market Educator 📈
Strategy OverviewThis strategy explores three forms of arbitrage in crypto derivatives trading across multiple exchanges (such as Delta Exchange, Shark Exchange, and CoinSwitch) via multi-exchange unified trading terminals like MirrorPip:Spot/Futures Price Arbitrage: Capturing temporarily wide price spreads between two exchanges by buying long on the cheaper exchange and shorting on the expensive exchange simultaneously.Funding Rate Arbitrage: Capitalizing on significant funding rate disparities (e.g., +0.1% to +0.4% per 8-hour or 3-hour period) by buying long where funding is paid/zero and shorting where funding payouts are extremely high, creating delta-neutral income.Implied Volatility (IV) & Expiration Arbitrage: Exploiting differences in option expiration times and implied volatility across exchanges by shorting option contracts with higher premium/earlier expiry and locking long legs on cheaper exchanges.Trade Rules & ParametersEntry Filters: Limit order execution to eliminate order slippage and ensure trading fee overhead (including taker/maker fees and taxes) does not exceed funding yield.Position Hedging: Simultaneously hold 1:1 opposing positions on two different exchanges to neutralize price market risk.Exit Rules: Unwind both long and short legs once funding rates equalize or options reach targeted time decay levels.
 The Trading Channel
This comprehensive multi-timeframe day trading strategy focuses on aligning entries with major market structure trends while timing entries off lower timeframe pullbacks.Key Strategy RulesHigher Timeframe (HTF) Market Structure: Identifies macro trend direction (e.g. 1-Hour chart) using major swing levels and HTF moving average filter to confirm higher highs/higher lows or lower highs/lower lows.Lower Timeframe (LTF) Execution: Trades on lower timeframes (e.g. 5-Minute chart) in the direction of the HTF major trend.Pullback Entry Trigger: Wait for price to pull back to/beyond the 20 LTF EMA without breaking the major structure level, followed by a momentum candle close back in the direction of the HTF trend.Stop Loss Placement: Placed just beyond the recent major/minor swing low for buys or swing high for sells.Take Profit Target: Fixed 2.4:1 Reward-to-Risk Ratio based on trade stop loss distance.
Strategy OverviewThis XAUUSD (Gold) scalping strategy combines candlestick pattern identification (Pin Bars and Engulfing patterns) with baseline trend filtering using a 50 Exponential Moving Average (EMA). Dynamic risk management is handled via the Average True Range (ATR).Inputs & ConfigurationEMA Period: 50 period trend filter.ATR Period: 14 period dynamic volatility calculation.ATR SL Multiplier: 1.5x ATR for stop loss placement.Risk/Reward Ratio: 1:1.5 target allocation.Entry RulesLong Entry: Price closes above 50 EMA AND either a Bullish Pin Bar or Bullish Engulfing pattern completes.Short Entry: Price closes below 50 EMA AND either a Bearish Pin Bar or Bearish Engulfing pattern completes.Exit RulesStop Loss: Set at 1.5x ATR distance from the entry price.Take Profit: Set at 1.5x the risk distance (1:1.5 Risk-to-Reward ratio).
Download the complete quantitative guide: Position Sizing Formulas, Prop Firm Drawdown Rules, and MQL5 Parameter Cheat Sheets.